When the agent pays: Identity, trust and fraud in agent-initiated payments
The Thredd Team
October 07, 2026
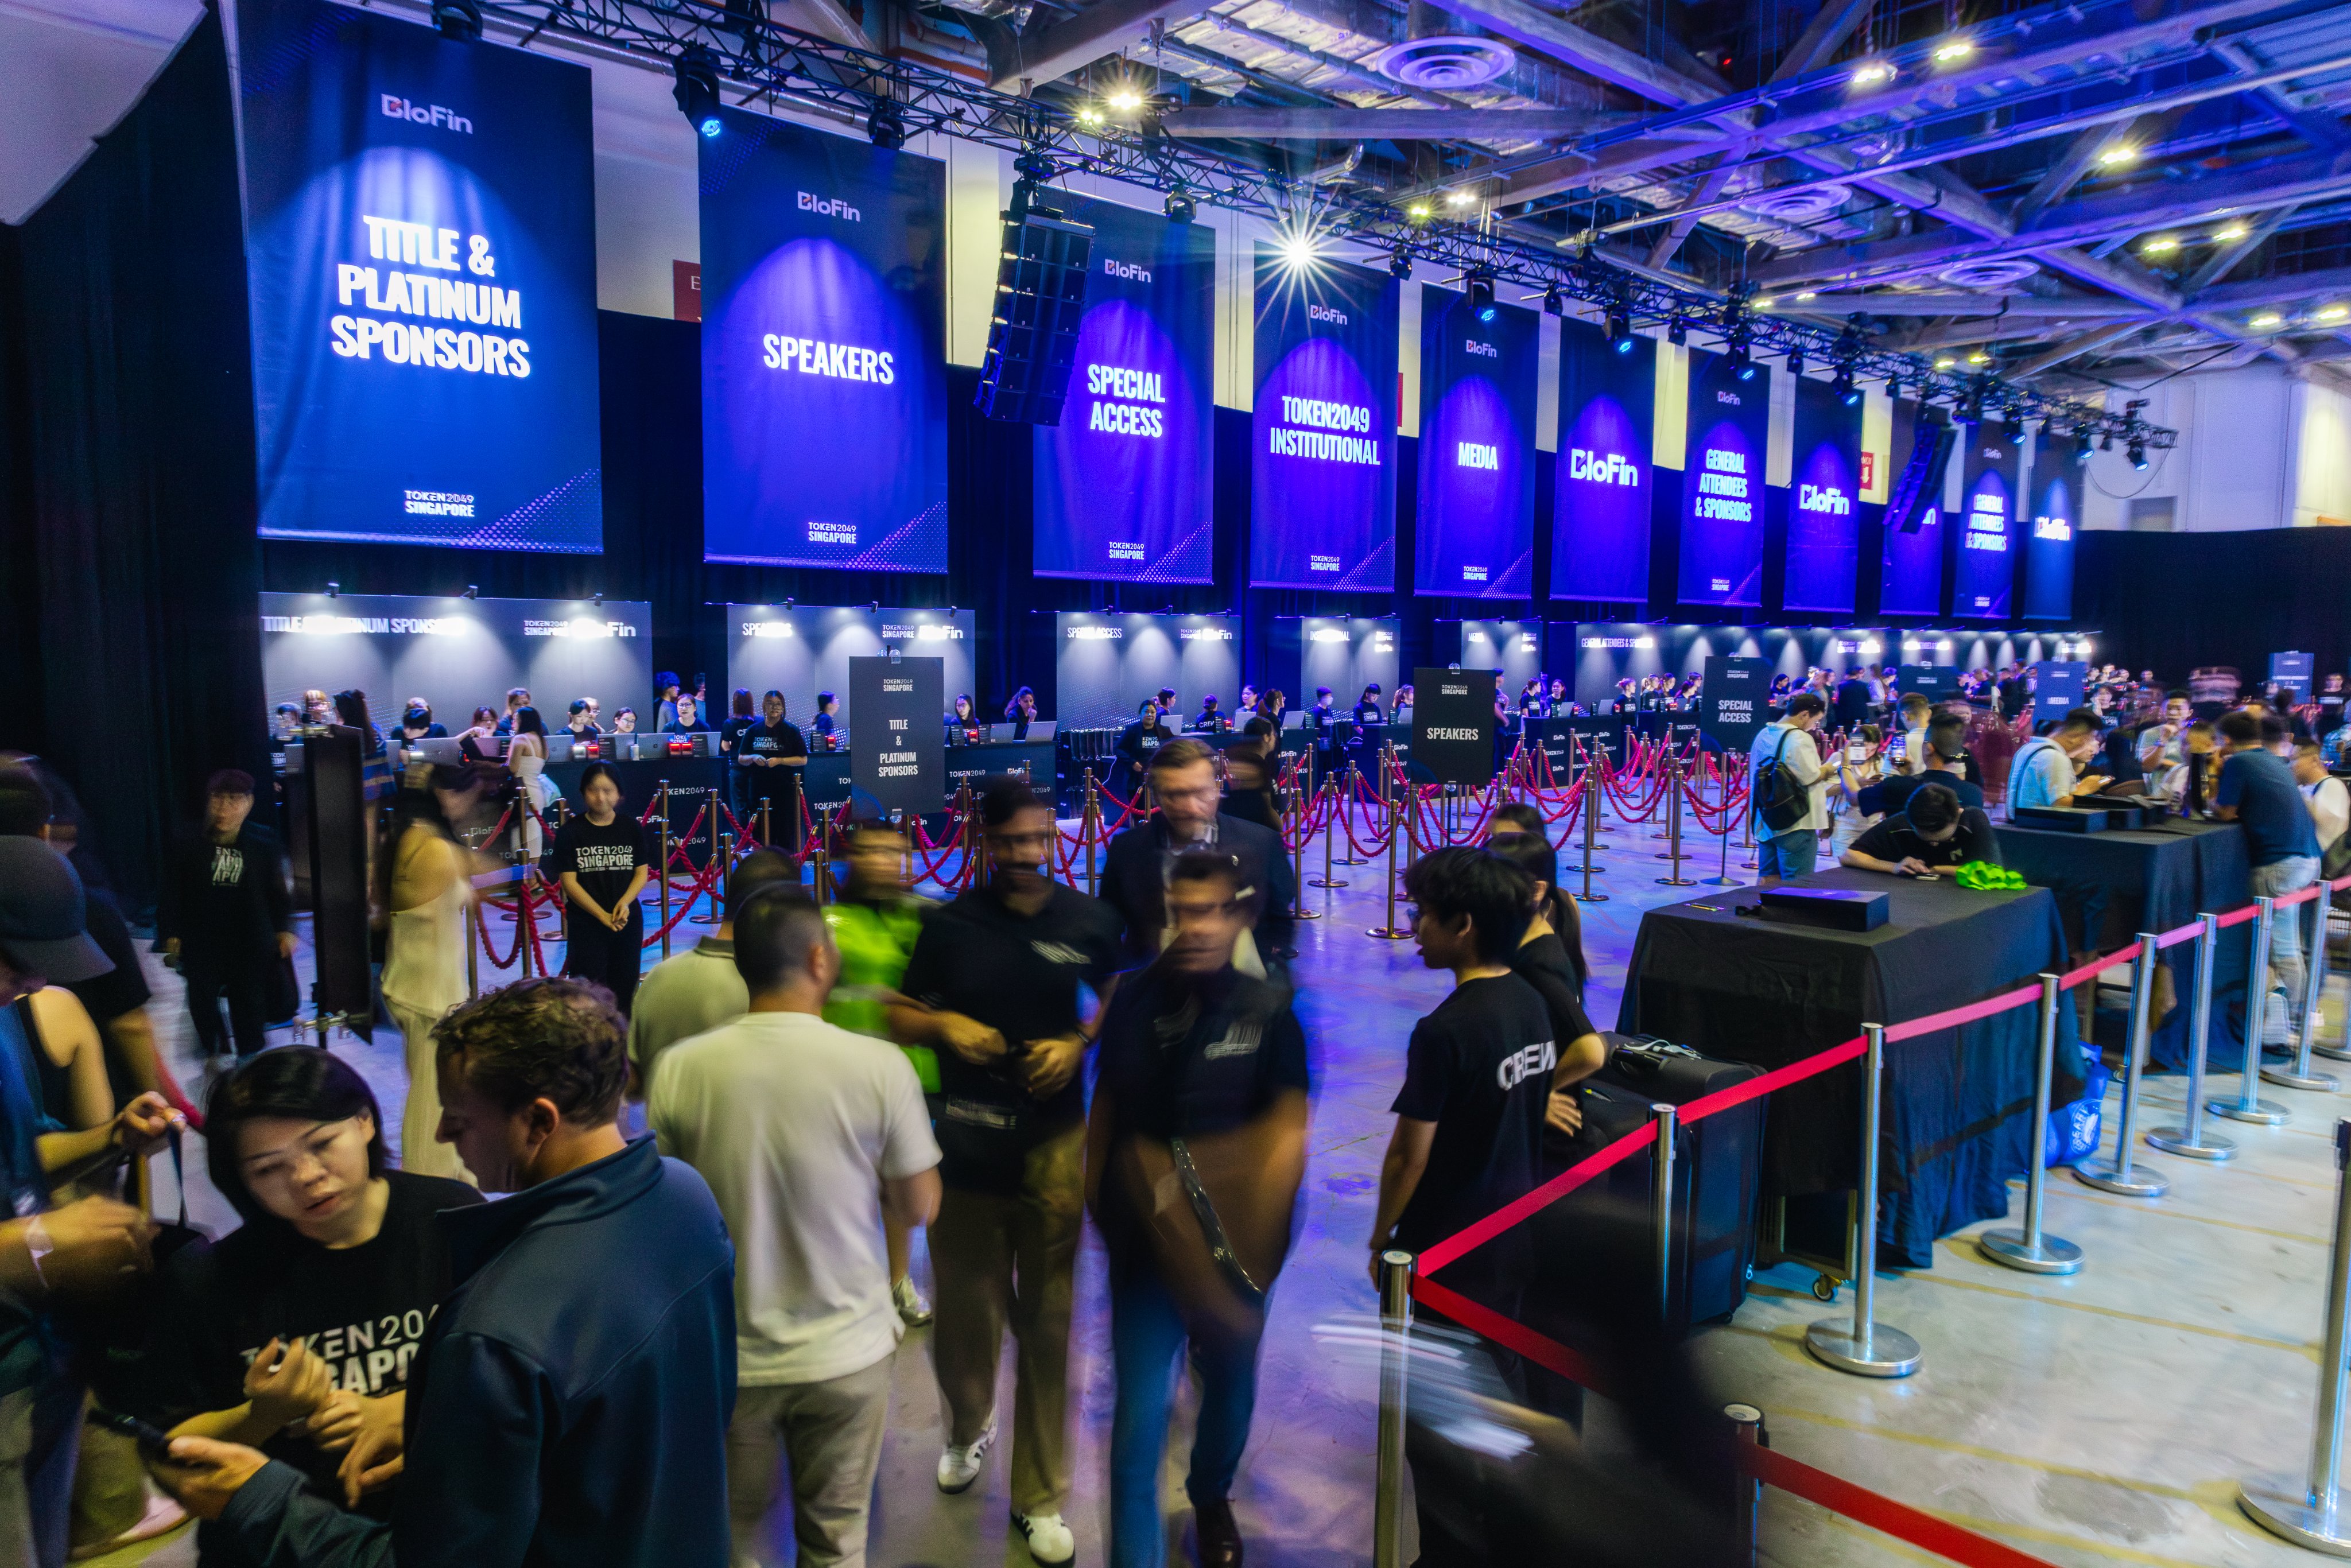
Token2049 bills itself as the world's largest crypto event. This year, much of its exhibition floor was about payments. "It's still very vibrant," Cecilia says, "but that vibrancy is now geared towards enterprise and solving real-world needs today."
We went because crypto-linked cards are already a significant part of what we process, particularly in Asia Pacific, through programmes such as Bybit and Reap. Stablecoins and AI are our focus this year, and they were the two main themes at Token2049 as well.
Card programmes were everywhere on the exhibition floor. For any established exchange or crypto wallet, a card is now standard. The data points the same way: monthly crypto card volume has grown from around $100 million to more than $1.5 billion in under three years, according to Artemis Analytics.
"Crypto cards for everyday spend are no longer a tagline. They're essential," Cecilia says. "If you're operating an exchange or a crypto wallet and you don't have a card programme, you're behind."
Crypto exchanges no longer want to be known only for crypto. They are adding tokenised real-world assets, gold, derivatives and CFDs to their platforms, with the aim of becoming their users' investment platform of choice.
That ambition leads straight back to cards. "You're attracting users to trade and invest with you, but you also want them to stay with your platform as long as possible," says Cecilia. A card gives users a reason to stay, which extends the user lifecycle.
Whoever puts in the right AI models and infrastructure, that can solve for trust, identity and fraud, will be the game changer in cards and payments."
Cecilia heard a different conversation about stablecoins this year. "It's no longer about whether I should use stablecoins in my business," she says. "It's in practice today, and adoption in B2B is huge." The numbers agree. B2B made up $226 billion of the $390 billion in stablecoin payments in 2025, according to McKinsey and Artemis Analytics.
The card networks are moving with it. Visa and Mastercard both now offer stablecoin settlement. Because stablecoins settle 24/7, settlement no longer stalls over the weekend. That helps schemes and BIN sponsors assess their settlement risk exposure, increases confidence in supporting new card programmes and helps money move more easily across borders.
The issuer market has grown quickly too. In the last 12 months, we have seen more fintech issuers enter the market that can support card issuing in 100+ markets.
Agentic commerce is where Cecilia sees the industry racing hardest. Visa, Mastercard and every serious fintech are working to build AI models that make money simpler to use without compromising identity and trust, and that trust layer is the part the infrastructure still needs to deliver.
"Whoever puts in the right AI models and infrastructure, that can solve for trust, identity and fraud, will be the game changer in cards and payments," she says. She expects it to still be a headline at Token2049 next year.
The two biggest card networks are taking different routes to that trust. Visa's approach is protocol-first: its Trusted Agent Protocol starts early in the journey, using signed messages that let a merchant recognise a trusted AI agent before checkout.
Mastercard's approach is decisioning-first, scoring the transaction at the point of payment. On 30 September it announced a probability score, now being tested in the US, that estimates how likely it is that an AI agent started a purchase. The aim is to give issuers the confidence to approve legitimate agent purchases instead of declining them.
Whichever route wins, every agent payment still ends in the issuer's authorisation decision. The trust, identity and fraud questions Cecilia raised sit with issuers and their processors as much as with the networks.
Crypto is borderless, and Cecilia believes crypto card programmes should be too, because their users are. In practice, licensing and regulation still limit how borderless a card programme can be, so the partner you choose matters. One of our clients uses a single Thredd connection to run market-specific programmes that meet local compliance requirements, while keeping one view of the whole portfolio.
Her bigger piece of advice is about timing. "Launch and learn," she says. "Only when you launch can you learn what your users want and don't want, and define your product and go-to-market strategy."
Across 130+ clients, we process over 2.5 billion transactions a year. The questions Cecilia heard in Singapore, about launching fast, settling in stablecoins and staying compliant across markets, are the ones we work through with clients every day.
Planning a crypto-linked or stablecoin card programme? Talk to our team about launching across markets with one processing partner.
The Thredd Team
October 07, 2026
The Thredd Team
July 27, 2026
The Thredd Team
July 22, 2026